Equity Release for UAE Property Owners
Equity Release Advisory for UAE Property Owners
Understand How Much Equity You Can Access, the Costs Involved, and Whether It Makes Financial Sense
Equity release lets you borrow against the value of your home without selling it. You keep the property. You access the cash. Finnequity finds the bank that will give you the most at the lowest rate.
Equity Release for UAE Property Owners
Equity Release Advisory for UAE Property Owners
Understand How Much Equity You Can Access, the Costs Involved, and Whether It Makes Financial Sense
Equity release lets you borrow against the value of your home without selling it. You keep the property. You access the cash. Finnequity finds the bank that will give you the most at the lowest rate.
How much you can release
UAE banks allow you to borrow up to 75% to 80% of your current property value, minus any outstanding mortgage. Here is how the calculation works.
|
Your situation
|
Amount
|
|---|---|
|
Property current value
|
AED 2,000,000
|
|
Outstanding mortgage balance
|
AED 700,000
|
|
Maximum FTV allowed (80%)
|
AED 1,500,000
|
|
Maximum new total loan
|
AED 1,500,000
|
|
Minus existing mortgage
|
AED 700,000
|
|
Maximum cash you can release
|
AED 800,000
|
Note: As per UAE Central Bank Regulation, equity release can only be used for purchase of a new properpty (ready or under construction) or renovation or remodeling of an exisitng property.
The exact amount depends on your bank, the property type, and the emirate. Finnequity gets you an accurate figure before you commit.
How Finnequity Assesses Equity Release Opportunities
Before recommending an equity release strategy, we evaluate:
Property valuation
Existing borrowing
Loan-to-value limits
Monthly affordability
Intended use of funds
Total financing costs
Alternative financing options
Long-term financial impact
This ensures clients understand the implications of increasing secured borrowing before proceeding.
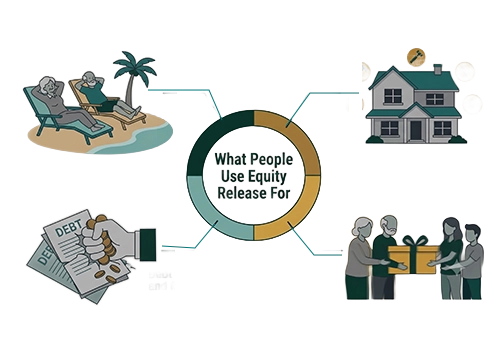
What people use equity release for
Buying a second property or investment asset.
Home renovation or extension.
Children's education or major life expenses.
Paying off higher-cost debts to reduce total monthly outgoings.
Business capital or investment.
Central bank restricts the usage of the funds to buy a new property in UAE or renovating/remodeling an existing property.
Important Considerations Before Releasing Equity
Equity release increases the amount secured against your property.
Clients should consider:
Increased monthly repayments
Property market fluctuations
Changes in personal financial circumstances
Total borrowing costs over time
Future refinancing needs
Retirement planning implications
Finnequity’s role is to ensure clients understand both the advantages and potential risks before making a decision.
What your free equity report includes
Your estimated maximum releasable equity based on current property values in your area.
Current equity release rates from the top banks in UAE.
A comparison of staying with your current bank versus moving to a new bank for the equity release.
The total monthly payment on the new loan.
A clear recommendation on the best bank and structure for your purpose.
Client Testimonials
What People Say About Us
"Was ready to just accept my bank's rate until a colleague mentioned Finnequity. They pulled quotes from 8 banks and found me something noticeably better. The broker walked me through every fee upfront, nothing hidden. Whole process felt far less stressful than I expected buying my first place here."
Bhaveshkumar P.
Jan 2025
"Buying our first home together and neither of us understood UAE mortgages at all. Asked probably too many questions but never once felt like a burden. Everything was explained in plain language, and replies on WhatsApp came fast, even outside normal hours. Made a confusing process feel manageable."
Hasnain & Um-e-Laila G.
Jan 2025
"Being self-employed I assumed getting approved would take forever or just not happen. Finnequity already knew which banks actually work with business owners like me, so we skipped the ones that would've rejected me. Approved in under three weeks with far less paperwork drama than I braced for."
Nikunj P.
Feb 2025
"Wanted an Islamic mortgage but wasn't sure it would even work out financially compared to conventional. They compared both side by side with real numbers, not vague explanations. Rate ended up close to conventional anyway. Nobody at branch level had ever laid it out for me this clearly before."
Rimma K.
April 2025
"Had the same mortgage rate for years without ever reviewing it, didn't think it mattered much. Finnequity ran the numbers and refinancing dropped my monthly payment by over AED 600. Wish I hadn't waited so long. The switch itself was handled entirely by them, I barely had to do anything."
Sharath S.
May 2025
"Was set on buying in Dubai until they broke down the actual upfront costs versus Sharjah for my budget. The registration fee difference alone changed my decision. Appreciated that they weren't pushing one option, just gave me the real numbers and let me choose what made sense for me."
Muhammad K.
July 2025
The process
Fill in the form. A Finnequity broker calls you within the hour to confirm your property details and purpose.
Within 24 hours you receive your free equity report showing the maximum releasable amount and the best current bank offers.
Finnequity manages the bank application, valuation, and full documentation. Most equity release applications complete in 4 to 6 weeks.
Find out your exact equity figure now
Property value and outstanding balance. That is all we need. Your free report arrives within 24 hours.
Ready to find out what you can borrow?
Fill in the form. A Finnequity broker will call you within the hour. No fees. No commitment.
Get free mortgage advice
Need More Help?
Call Now
Email Address
Location
Meydan Grandstand, 6th floor, Meydan Road, Nad Al Sheba, Dubai, U.A.E.